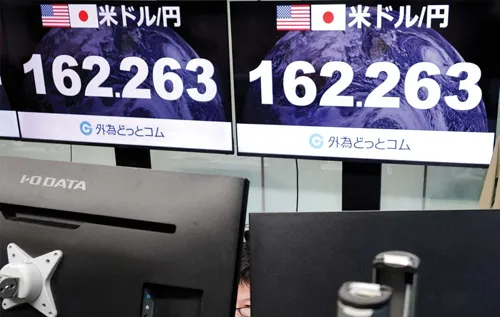
Japan and the US jointly intervened in currency markets on July 31 to prop up a historically weak yen, but analysts deem the effort temporary. The article argues that deeper structural issues—a wide yield gap between US (4.7%) and Japanese bonds (2.8%), low Japanese borrowing costs, and yen carry trade incentives—will persist unless Japan raises interest rates and increases investment in AI and growth sectors. The yen weakened again by August 11, suggesting intervention alone cannot address fundamental economic imbalances.
← Back to all articles